Could capital allowances reduce the cost of investing in port and harbour infrastructure?
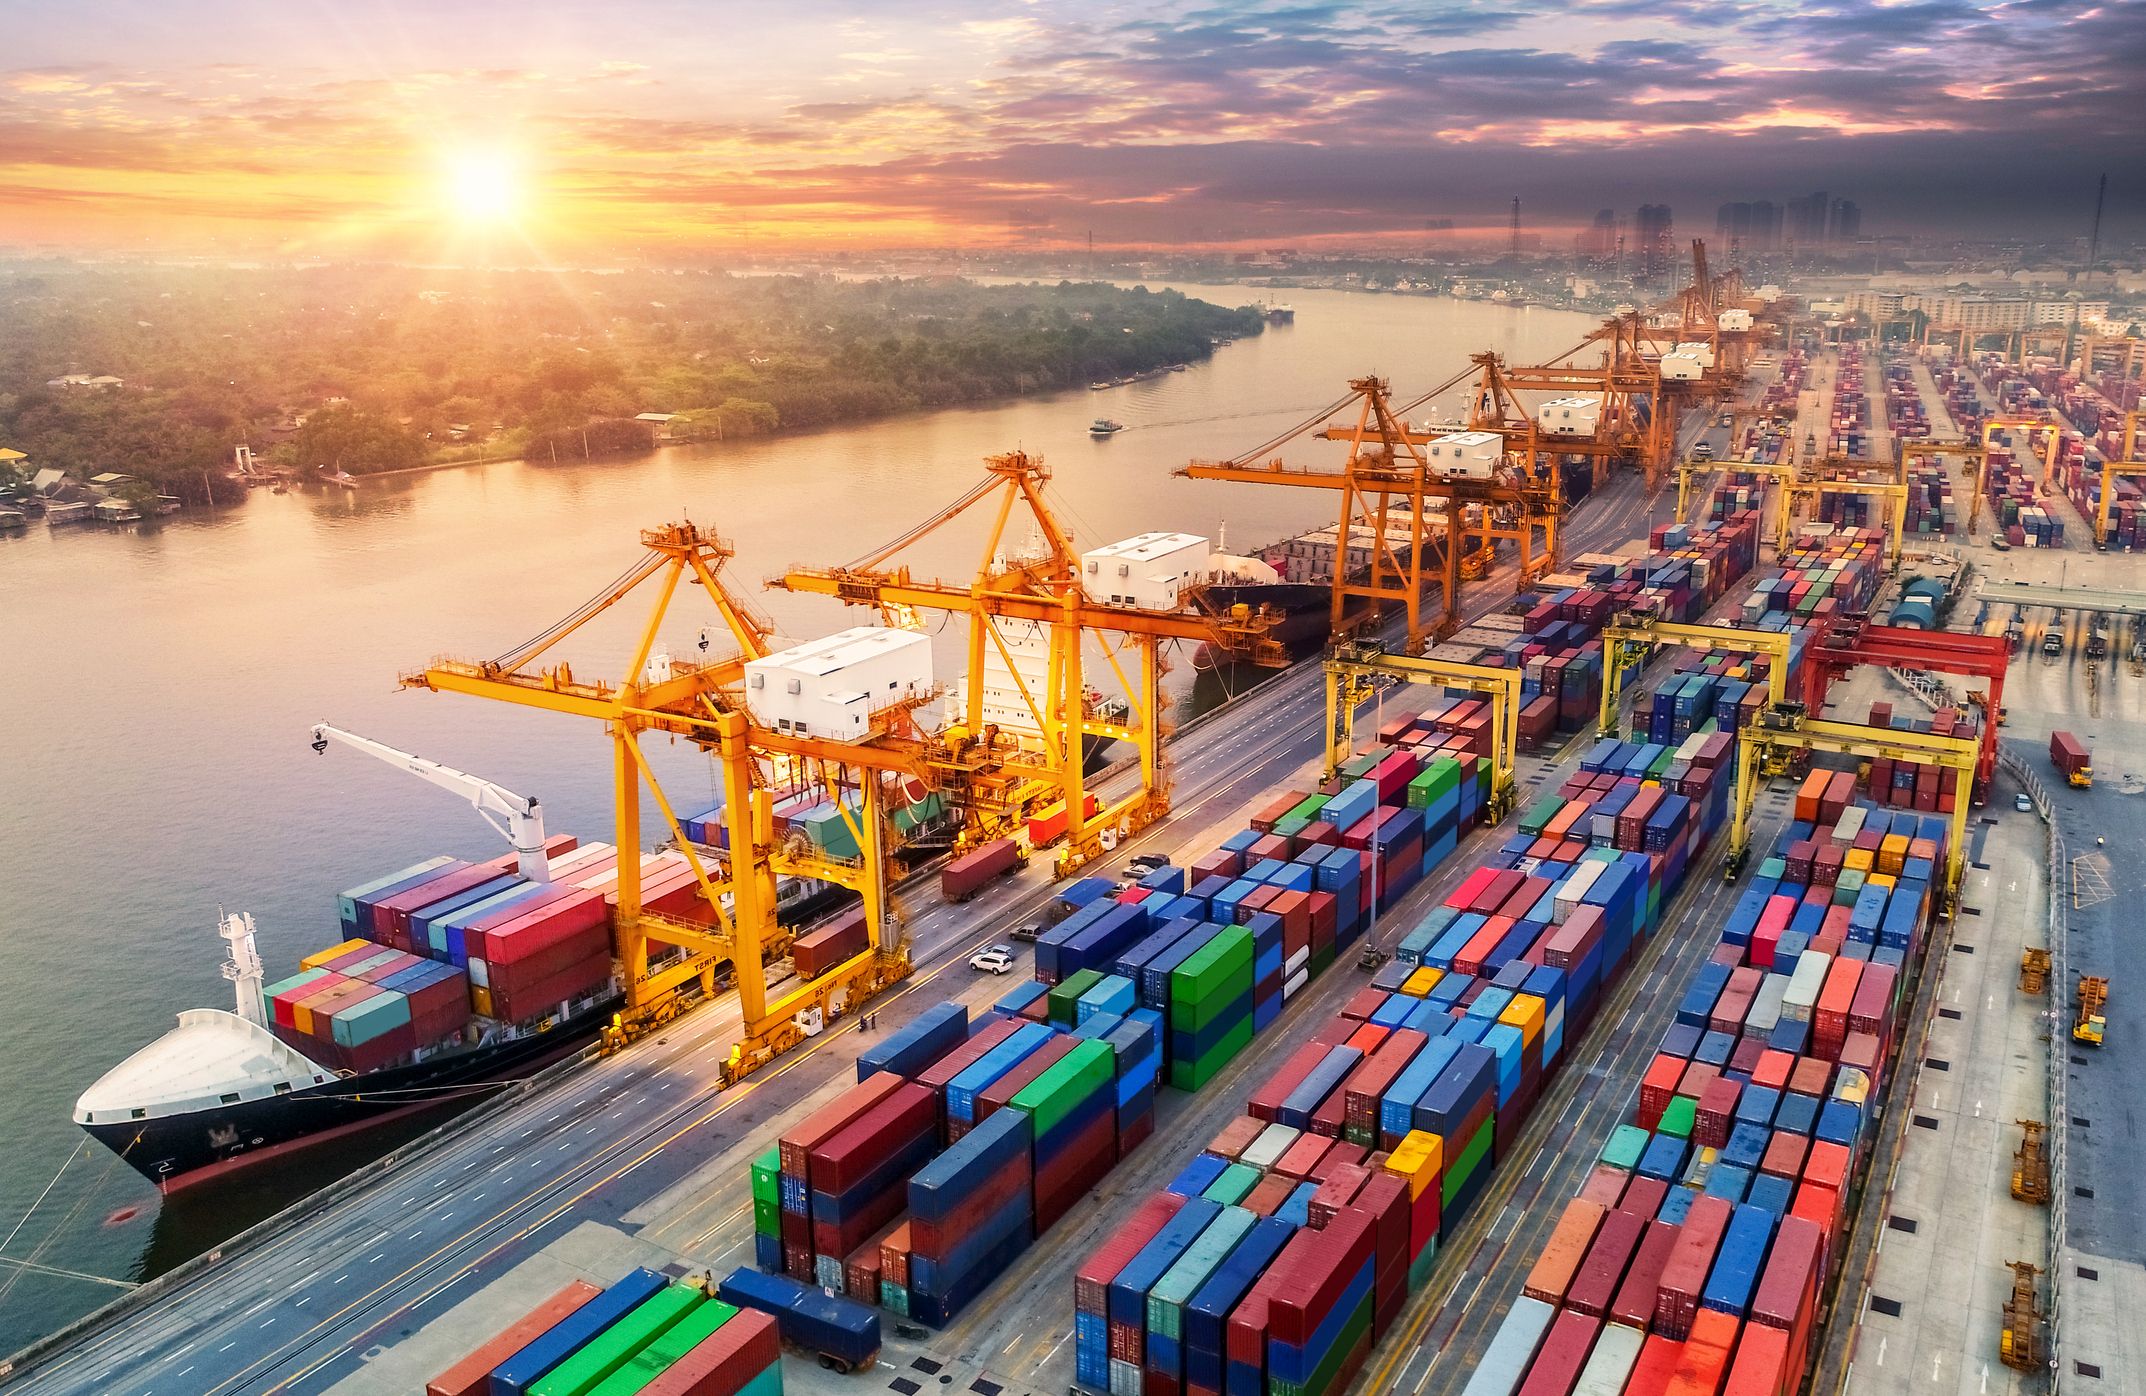
The UK has approximately 120 commercial ports located around the country.
They vary in size and comprise a mixture of privately owned ports, trust ports and local authority-owned ports. There are also 10 Freeports located in England and Wales, and two Green Freeports located in Scotland. Not all Freeports are related to the maritime sector, with the East Midlands Freeport being centred around East Midlands Airport.
The Ports and Harbours sector requires significant capital investment due to the nature of its infrastructure and equipment needs. Businesses operating in the sector should consider how the UK Capital Allowances regime can help reduce the tax payable on the profits they generate.
What capital allowances are available?
A range of capital allowances and other forms of tax relief may be available. The level of tax relief that can be realised will depend on the type of tax paid, as well as when and how the expenditure was incurred. The allowances available include Plant and Machinery Allowances (PMAs), Structures and Buildings Allowances (SBAs), Dredging Allowances and specialist reliefs such as Land Remediation Relief (LRR), which relates to the decontamination of land and the removal of asbestos.
The three key points for any business claiming allowances are that it must have incurred the expenditure, be a UK taxpayer, and have an interest in the land to which the capital allowances claim relates.
An important tribunal decision
The Mersey Docks and Harbour Company Limited secured a favourable First-tier Tribunal (FTT) judgment in December 2025 in relation to the construction of a quay wall at a new deep-water container terminal at the Port of Liverpool. The decision allowed £57m spent on the new quay wall to be treated as plant, making it eligible for capital allowances.
HMRC appealed the decision, and the appeal was heard by the Upper Tribunal (UT) in July 2026, with the judgment expected to be published later in 2026. This is an important case for the ports and harbours sector, as it could create valuable opportunities for businesses investing in infrastructure improvements.
Freeports and Scottish Green Freeports
Freeports in England and Wales and Scottish Green Freeports are special economic zones where normal tax and customs rules do not apply. Scottish Green Freeports also support net zero ambitions and wider decarbonisation strategies. The tax reliefs available vary between zones but can include enhanced plant and machinery allowances, an increased SBA rate from 3% to 10%, as well as more favourable reliefs for property and land transactions and business rates.
The energy sector
A major opportunity for the UK Ports and Harbours sector is the transition from traditional fossil fuel-based industries towards renewable energy infrastructure, alternative fuels, and the decarbonisation of marine transport. Ports involved in the deployment of renewable energy assets will require strengthened quaysides, increased crane lifting capabilities, and large covered manufacturing and assembly buildings. The servicing of new renewable energy assets will also drive demand for smaller harbours to host maintenance and servicing hubs. This new infrastructure will require significant capital investment, some of which may qualify for valuable capital allowances relief.
Shipping and net zero
The shipping sector is currently going through a decarbonisation process in relation to the fuels used to propel ships. The current use of heavy fuel oils (HFOs) contributes approximately 3% of global CO2 emissions. A number of alternative fuels have been proposed, with some already being adopted across the sector. For the Ports and Harbours sector, this will affect fuel bunkering, storage, and tank-to-ship refuelling systems. Existing bunkering and refuelling systems may need to be upgraded or replaced depending on the choice of alternative fuel.
Upgrading or replacing existing fuel bunkering and supply systems will require capital investment. This expenditure may attract valuable tax relief through the UK Capital Allowances regime.
The future for UK Ports and Harbours
Changes within the UK energy sector and global marine shipping may require the UK Ports and Harbours sector to invest in new infrastructure or update existing facilities. Businesses planning new infrastructure projects should consider capital allowances at the earliest stage of financial appraisal. Identifying relief opportunities early can help maximise available tax savings and improve project viability.
How we can help
Are you planning to construct or update port or harbour infrastructure? Speak to Robert Winters, our specialist Energy, Infrastructure & Sustainability or Construction & Property Incentives teams, or your usual Johnston Carmichael contact to discuss your project.