How capital allowances can support engineering and manufacturing businesses
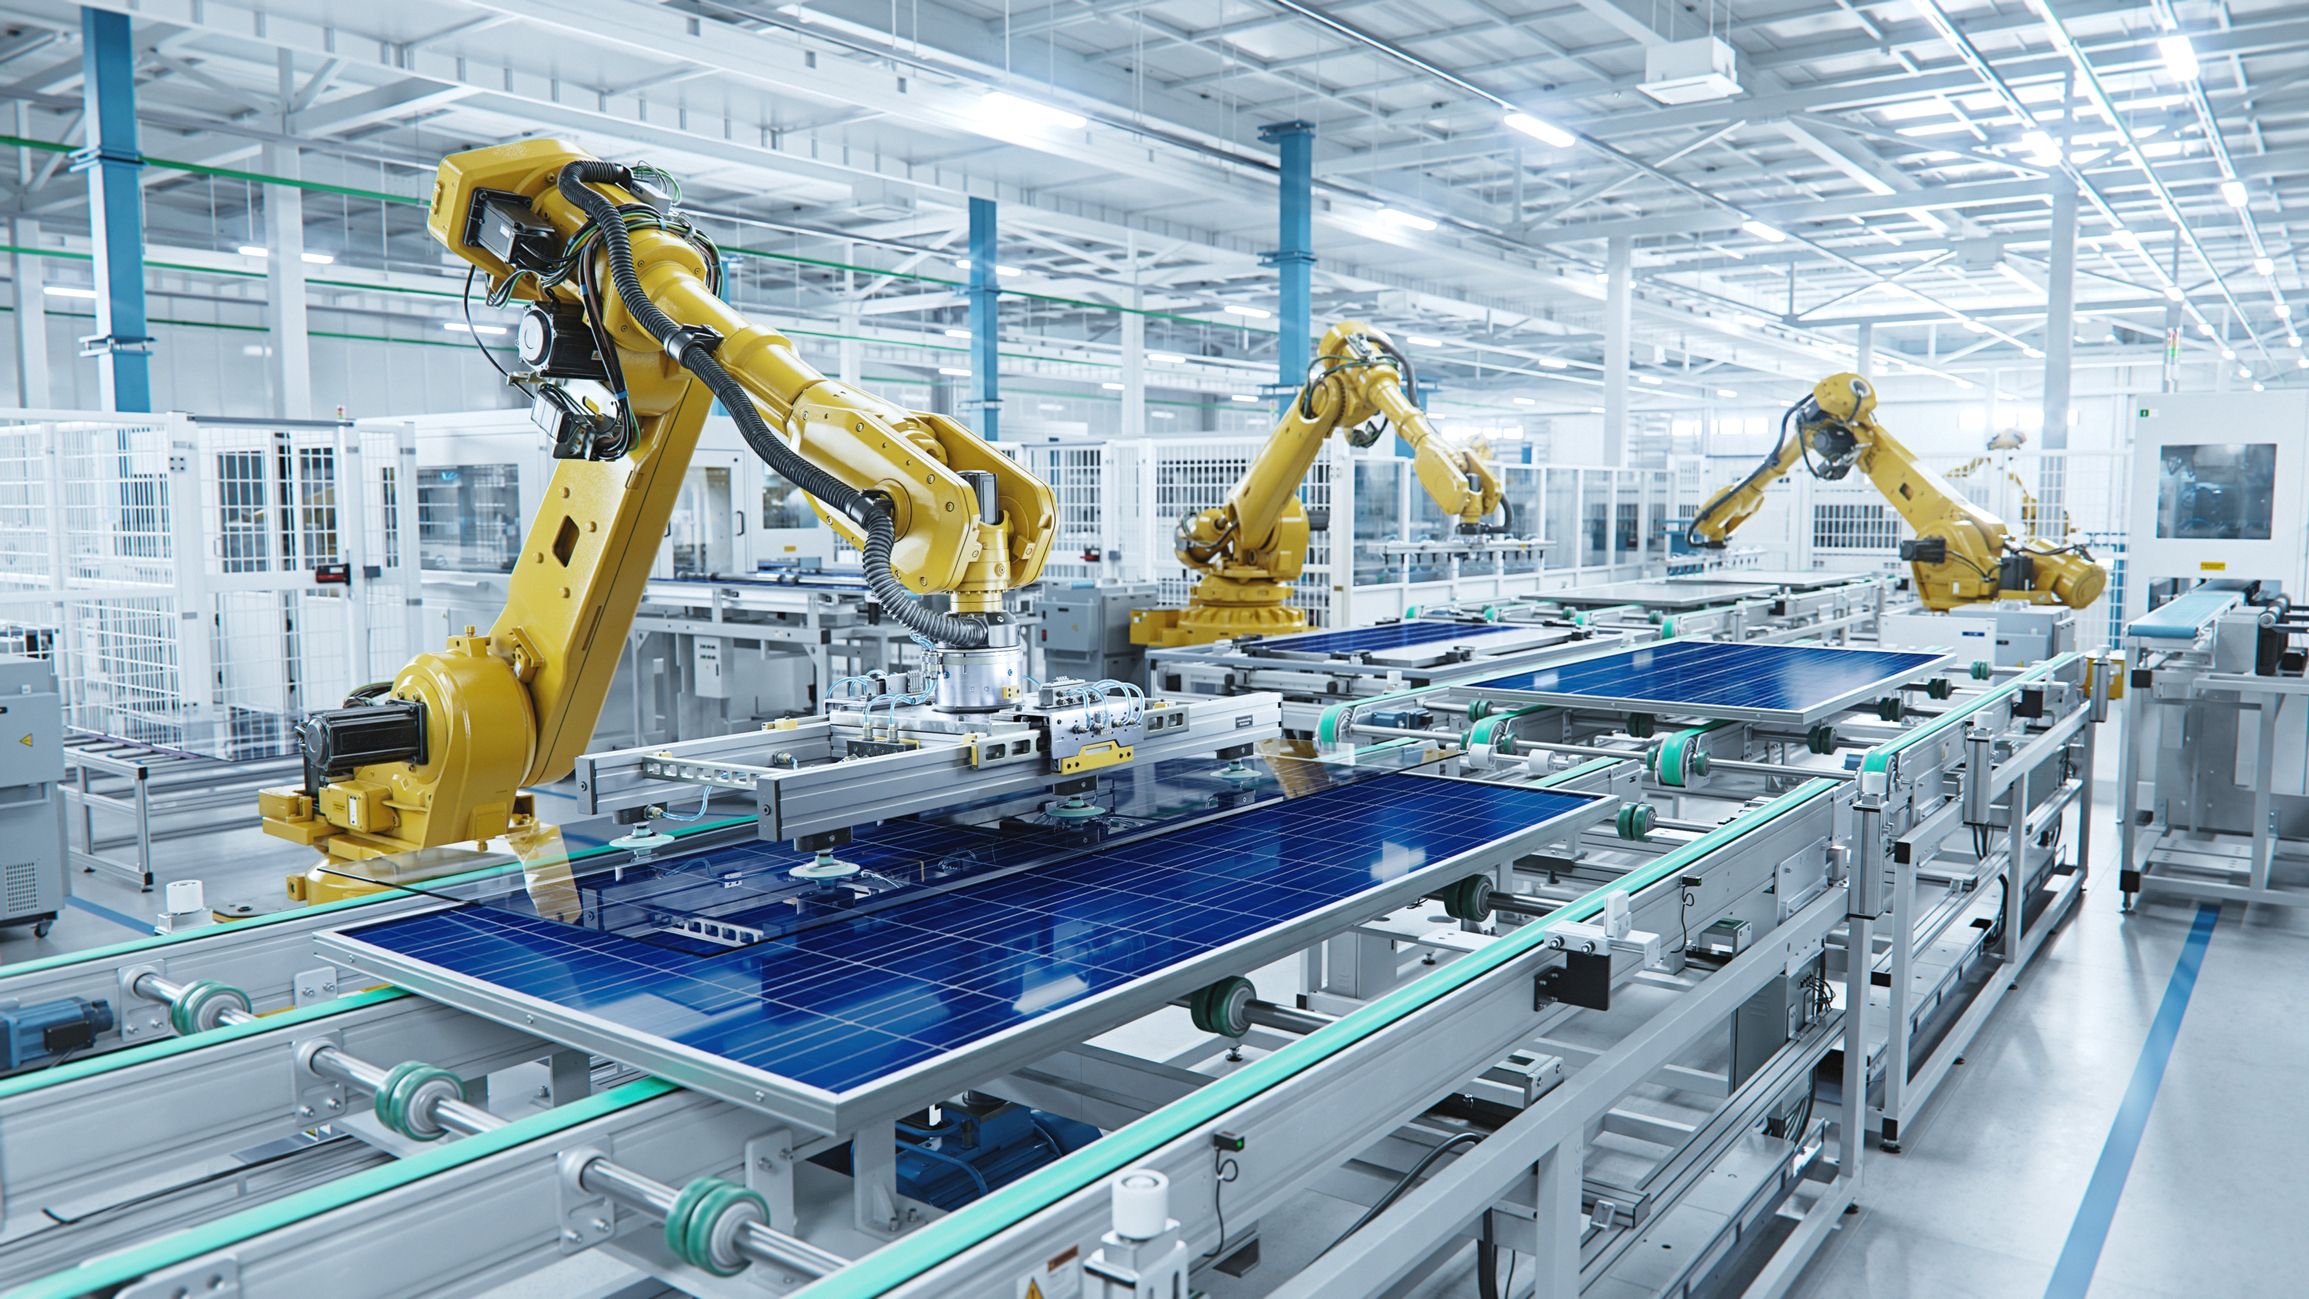
Engineering and manufacturing businesses invest heavily in the assets that keep operations moving. From production facilities and machinery to electrical systems and specialist equipment, these investments are essential for growth, efficiency, and competitiveness.
Constructing industrial buildings is a process that brings with it a host of unique and complex challenges, including rising build costs, increased material and labour costs, site preparation, planning conditions, utility connections and phased fit-outs.
What many businesses don't realise is that a significant proportion of these costs may qualify for tax relief through capital allowances.
Capital allowances reduce the amount of tax a business pays by providing relief on qualifying capital expenditure. When claimed correctly, they can improve cash flow, support future investment, and ensure businesses receive the relief they're entitled to.
Qualifying assets can include machinery and equipment used in production, as well as elements of the buildings where those activities take place. This may include:
- Structural components such as floors, walls, roofs, windows, and doors.
- Electrical and mechanical systems.
- Fixtures and fittings.
- IT and telecommunications infrastructure.
- Production and manufacturing equipment.
Getting the classification of expenditure right is essential. Different assets qualify for different types of allowances, and incorrect treatment can result in underclaimed relief or future tax adjustments.
What capital allowances are available?
The level of relief available depends on the type of asset, the tax position of the business, and when the investment was made.
Capital allowances rates have varied over time, with rates determined by the Government of the day. Successive UK Governments have changed these rates to stimulate investment by increasing the level of relief available, or to restrict relief and increase tax receipts.
For engineering and manufacturing businesses, understanding which allowances apply can help improve cash flow, support investment decisions, and ensure that available tax relief is not missed.
Plant and machinery allowances
Plant and machinery expenditure is generally allocated to either the special rate pool or the main rate pool, depending on the nature of the asset. The special rate pool includes expenditure on integral features within buildings and certain long-life assets, while the main rate pool covers plant and machinery that does not fall into these categories and is not treated as a short-life asset.
The relief available depends on the type of asset, the business’s tax position, and when the investment was made. This can include writing down allowances of 6% or 14%, as well as First Year Allowances (FYAs) of 40%, 50%, or, in some cases, 100%.
Structures and buildings allowances
Structures and Buildings Allowances (SBAs) were introduced at 2% per annum on a straight-line basis and increased to 3% in 2020. While welcome, they remain a slow form of relief, with the benefit realised over 331/3 years.
For example, if £750,000 of expenditure on a new building qualifies for SBAs, this would produce relief of £22,500 per annum for 33 years, with a further £7,500 in the final one-third year.
A taxpayer subject to corporation tax at 25% would obtain a cash tax saving of £5,625 per annum on the £22,500 of tax relief.
Other specialist allowances
Some businesses may also be able to benefit from more specialist reliefs.
Land Remediation Relief (LRR) is an incentive available to corporation tax payers that allows companies to claim a 150% tax deduction on costs incurred in cleaning up contaminated land and buildings. This includes the removal of asbestos inside buildings and from asbestos cement roof sheet coverings.
This form of tax relief is particularly useful for engineering and manufacturing companies undertaking refurbishment works on older buildings where asbestos fireproofing, insulation and roof coverings were used in the original construction. However, a corporate taxpayer can only claim LRR if it was not the original polluter.
Don't overlook the Annual Investment Allowance
Last but not least, any engineering and manufacturing business should not overlook the importance of the Annual Investment Allowance (AIA). Currently set at £1 million, it allows qualifying expenditure to be written off in full in the year it is incurred, delivering immediate tax relief and improving cash flow.
What is important?
Information is critical. Good-quality cost data is the backbone of any capital allowances claim. Descriptions of the works undertaken, evidence of expenditure incurred and photographs are all essential in creating an audit trail that supports the claim.
Engineering and manufacturing is a capital-intensive sector. In addition to the buildings required to house manufacturing and engineering equipment, businesses must also consider the cost of the equipment itself.
The UK Capital Allowances regime allows taxpayers to claim tax relief against profits where they have incurred expenditure on plant and machinery, structures and buildings used in the course of their business activities.
How we can help
Given the technical nature of the capital allowances legislation and the evidence required to complete a claim for capital allowances, taking advice early can help ensure claims are accurate, compliant, and deliver the maximum benefit available.
If you would like to discuss this further, don't hesitate to get in touch with a member of our Construction & Property Incentives or Engineering & Manufacturing teams. You can also fill in the short form below.